3Q 2026 URA Real Estate Statistics: Prices Continue to Climb Despite Lower Transactions in Quarter; Fuelled by Landed and OCR (Non-Landed) Market Segments
Press Release23 Oct 202610 min read

According to the Urban Redevelopment Authority (URA), private home prices rose 1.4% quarter-on-quarter (q-o-q) in 3Q 2026, continuing the steady growth seen in the previous quarter’s 0.5% increase. The Private Property Price Index (PPI) now stands at 222.5.
Average quarterly PPI growth now stands at 0.9%, in line with the corresponding period in 2025.
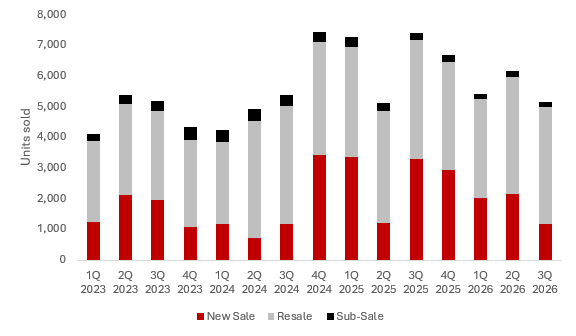
Meanwhile, total private home transactions fell to 5,146 units, down 16.3% q-o-q. This marks the lowest number of transactions in a quarter for 2026, and the lowest observed since 2Q 2025.
Price index growth in the quarter could be attributed to the launch of highly anticipated projects such as Amberwood at Holland, Dunearn House, and Lentor Gardens Residences. The latter two projects received a positive reception, selling over two-thirds of their available stock and helping drive price growth.
Amberwood at Holland, positioned as a premium CCR project, launched 70 (of its total 212 units) in September and sold 25 of those units to date. Notably, the bestselling floor plates were the 4-bedroom flexi and 4-bedroom premium units. This reflects a trend of larger units gaining traction during the quarter.
In September, new sales shifted toward higher price brackets: homes priced below $2.5 million made up 38.8% of new non-landed private home sales, excluding ECs, down from 60.3% in August. Meanwhile, the $2.5 million to $3 million range accounted for 23.1% of sales, up from 13.5% the previous month.
“Despite a more modest increase in prices observed in 2Q 2026 and 1H 2026 overall, resulting in lower launch volume and homebuyer activity due to seasonal factors such as the Chinese New Year holidays, as well as the June school holidays, we have witnessed an uptick in prices in the latest quarter (3Q 2026).
In 3Q 2026, the URA price index rose 1.4% even as sales volume fell quarter-on-quarter.
“Price gains in landed homes and non-landed properties in the Outside Central Region supported the increase, with prices rising 2.9% and 2.3%, respectively. This suggests that demand remained firm for certain segments and locations, even as fewer homes changed hands overall,” said Marcus Chu, Chief Executive Officer, ERA Singapore.
As with the new sales market, the seasonal lull also affected the resale market, reducing resale transactions from 3,813 in 2Q 2026 to 3,801 in 3Q 2026. Resale transactions accounted for 73.9% of all sales transactions this quarter, compared with 62% in the previous quarter.
“Resale volume could have accounted for a higher share of all sales transactions this quarter due to a leaner pipeline of new launches. 52.4% of resale transactions involved OCR condominiums, indicating resilient demand from owner-occupiers and genuine demand for homes,” said Chu.
Likewise, sub-sale transactions also fell from 194 in the second quarter to 162 in the third quarter. Sub-sale transactions accounted for 3.1% of all sales transactions, marginally lower than the 3.2% recorded in the previous quarter.
Based on caveats lodged for resale condominiums, Riverfront Residences recorded the most activity in the third quarter, with 33 transactions, followed by D’Nest (29 transactions). Normanton Park and Treasure at Tampines tied for third place with 27 transactions each.
Chart 1: Breakdown of private home transactions (excluding ECs) by type of sale
Source: URA as of 23 October 2026, ERA Research and Market Intelligence
New Sale and Supply Pipeline
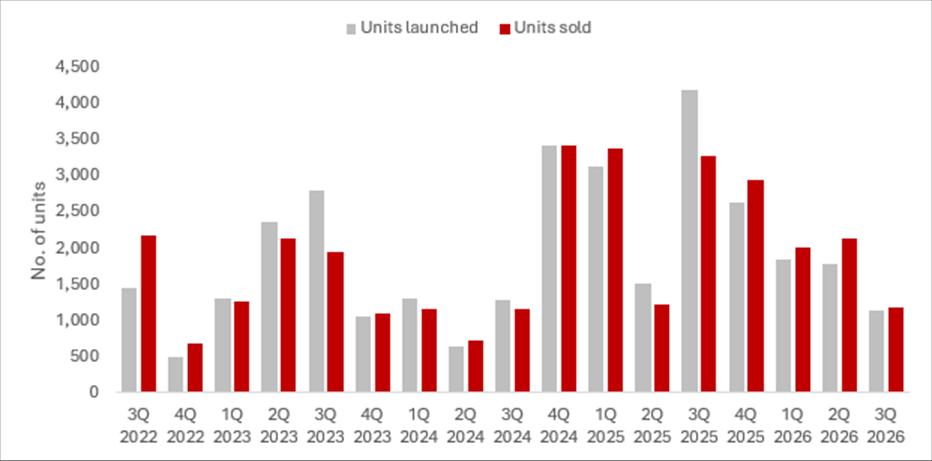
In total, developers sold 1,183 new homes in 3Q 2026, a 44.7% decline from 2,141 units in the previous quarter.
Developers also launched fewer homes, totalling 1,140 units, down from 1,783 in the previous quarter, continuing a downward trend from 1,844 in 1Q 2026.
Projects launched in the quarter included Amberwood at Holland (CCR), Dunearn House (CCR), and Lentor Gardens Residences (OCR).
However, with a smaller pipeline of new launches in 3Q 2026, buyer interest remained firm, signalling strong consumer confidence in Singapore’s new home market.
Despite a tepid new supply, underlying demand remained firm, with projects continuing to attract strong take-up. Projects entering the market continued to draw substantial interest, reflecting sustained buyer confidence despite global uncertainty. This has contributed to the 1.4% increase in the price index.
Chart 2: New Homes Launched and Sold (Excluding ECs)
Source: URA as at 23 October 2026, ERA Research and Market Intelligence
“Although Dunearn House in the CCR and Lentor Gardens Residences in the OCR cater to different buyer profiles, both achieved strong sales by meeting clear demand for homes with compelling location attributes and long-term growth potential. Their launches were well timed to capture interest from genuine homebuyers and investors who value each location's fundamentals—from Turf City's established appeal and planned transformation to Lakeside’s MRT access and the upgrader pool, as well as the MRT infrastructure around Lentor. This contributed to take-up rates of over 60%, a key factor driving the growth in the price index observed in the quarter,” said Chu.
No ECs launched in 3Q 2026, contrasting with the fanfare around the launches of Coastal Cabana and Rivelle Tampines earlier in the year. Therefore, we observed that EC transactions in 3Q 2026 mainly consisted of buyers snapping up remaining stock from these projects.
In May 2026, measures were implemented by the Ministry of National Development (MND) that is expected to impact the launch pricing and performance of future EC projects. These measures included extending the Minimum Occupation Period (MOP), removing the Deferred Payment Scheme (DPS), and increasing wait times for second-time buyers.
With the changes directly affecting future EC launches and GLS sites, EC homebuyers who may have been on the fence might be prompted to move on EC projects currently on the market, which offer greater flexibility under the previous EC regulations.
The government announced more changes to the EC market during the National Day Rally in August. A key change is raising the monthly income ceiling by $2,000 to $18,000, widening the pool of eligible EC buyers.
Unsold stock (completed and uncompleted units) increased 26.7% q-o-q to 19,076 units in 3Q 2026. This follows the successful launch of three new projects during the quarter, and a total of eight projects (including EC) earlier in 1H 2026.
A further 3,559 private residential units (including ECs) were completed in 3Q 2026. Excluding ECs, the full-year total for 2026 is expected to be 6,282 units, marginally higher than 2025’s count of 6,123 units. The mass completion of these private residential units added to the existing unsold inventory, which we expect buyers to snap up in the coming months.
By the end of 3Q 2026, 44,738 private residential and EC units had received planning approval, with 20,300 still unsold. A further 12,508 unsold units had not yet received planning approval. Together, these figures point to a potential pipeline of about 32,800 units that could be offered for sale over the next one to two years. This includes approximately 4,745 units on the 2H 2026 GLS Confirmed List, of which 735 are EC units.
Resale & Sub Sale
During the third quarter, 3,801 resale transactions for non-landed residential properties were recorded, remaining consistent with the 3,813 transactions in the previous quarter.
The moderate number of resale transactions this quarter may reflect the seasonal lull typically seen during the seventh lunar month.
Sub-sale volume also fell in the third quarter, down from 194 deals last quarter to 162 this quarter. This quarter’s sub-sale volume is significantly lower than the 235 sub-sale transactions recorded in 3Q 2025.
Landed
In 3Q 2026, 588 landed homes were transacted, the highest quarterly volume recorded so far this year. This occurred even as overall private home transactions fell to their lowest level in 2026, suggesting that demand for landed homes remained resilient despite a less active market.
The contrast also highlights differing buyer activity across property segments, with landed homes continuing to attract buyers even as fewer private homes changed hands overall.
Landed home prices also rose 2.9% q-o-q in 3Q 2026, continuing the 2.5% growth seen in the previous quarter. This continued price growth reflects sustained demand in the segment, supported by Singaporean buyers’ eligibility to purchase landed homes without special approval and the housing equity available to some households.
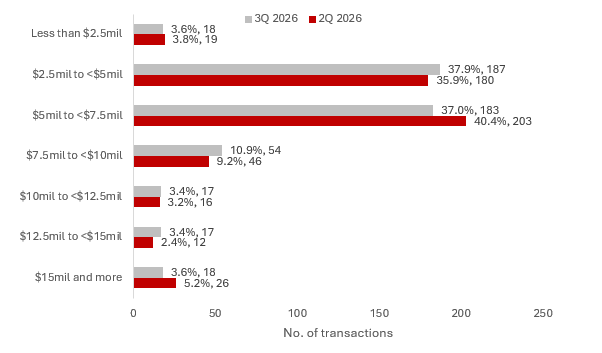
The price increase could be attributed to more landed homes fetching at least $5 million, with the number rising to 308 this quarter.
Notably, 206 (40.4%) of landed homes sold for $5 million to $7.5 million in 2Q 2026, accounting for most of the quarter’s transactions.
“Landed homes continue to attract buyers for their long-term value and established appeal. While financing conditions also influence purchasing decisions, sustained interest reflects buyers’ confidence in the segment,” added Chu.
Chart 2: Landed Price Quantum 3Q 2026 versus 2Q 2026
Source: URA as of 23 October 2026, ERA Research and Market Intelligence
Rental
The All-Residential Rental Price Index rose 1.3% q-o-q in 3Q 2026, up from 0.7% in the previous quarter. Overall rents for non-landed properties rose 1.2% q-o-q, significantly higher than the 0.4% increase recorded in the previous quarter. In contrast, landed property rents recorded a smaller increase of 2.1% q-o-q in 3Q 2026, compared to the rise of 2.7% in after the flattish 0.1% in 2Q 2026.
Among market segments, only the CCR non-landed market declined 0.3% q-o-q. This contrasts with the previous quarter, when rents for CCR condominiums rose 1.2% q-o-q, RCR rents remained flat, and OCR condominiums fell 0.3% q-o-q.
This quarter, RCR and OCR non-landed residential properties saw their rental index increase by 1.5% q-o-q and 3.1% q-o-q, respectively.
Upcoming Launches
3Q 2026 saw the successful launch of Amberwood at Holland, Dunearn House, and Lentor Gardens Residences. These three projects are part of a leaner 2H 2026 launch pipeline, with only Lucerne Grand and Thomson Reserve scheduled for 4Q 2026.
Overall, we expect around 2,765 units to launch in 2H 2026, compared with 3,627 units in 1H 2026.
Table 2: Upcoming New Home Launches in 4Q 2026
No. | Est. Preview | Project | Market Segment | Location | District | Developer | Tenure | Estimated number of units |
1 | Oct 2026 | Serra Residences | CCR | Novena | 11 | Far East | Freehold | 133 |
2 | Oct 2026 | Lucerne Grand | OCR | Lakeside | 22 | CDL | 99 LH | 570 |
3 | Oct 2026 | Thomson Reserve | RCR | Upp Thomson Rd | 10 | UOL/ Capitaland/Singapore Land Group | 99 LH | 1,268 |
Source: ERA Project Marketing
Market Outlook
Based on the 3Q 2026 URA quarterly report, overall private property prices increased by 1.4%. It remains on track to reach ERA’s earlier forecast of 3% to 5%.
Singapore is recognised as a safe haven amid global uncertainties thanks to stable governance, a strong Singapore Dollar, and a resilient property market. Despite global market challenges, Singapore's residential property sector remains largely optimistic for the near future. Over time, Singapore has built a reputation as a leading wealth hub in the region, with its real estate regarded as a high-quality asset that provides steady rental income and strong capital appreciation.
With Singaporeans' strong belief in real estate investment, much of the expected increase in wealth transfer will likely benefit this market. We already see older homeowners downsizing to unlock housing equity for liquidity, while younger buyers receive parental support for property purchases. Consequently, this capital flow will sustain long-term demand and price growth across Singapore's residential market.
In 2026, the private residential market is expected to remain resilient, supported by moderate price growth driven by strong owner-occupier demand and ongoing right-sizing trends. Healthy take-up rates from recent project launches reinforce this positive outlook. This underlying demand has also prompted developers to commit to new projects, suggesting that the development pipeline and future housing supply will remain supported by strong market fundamentals.
END
For media queries, please contact:
Eugene Syn
PR Manager
eugene.syn@era.com.sg